Cash & Margin
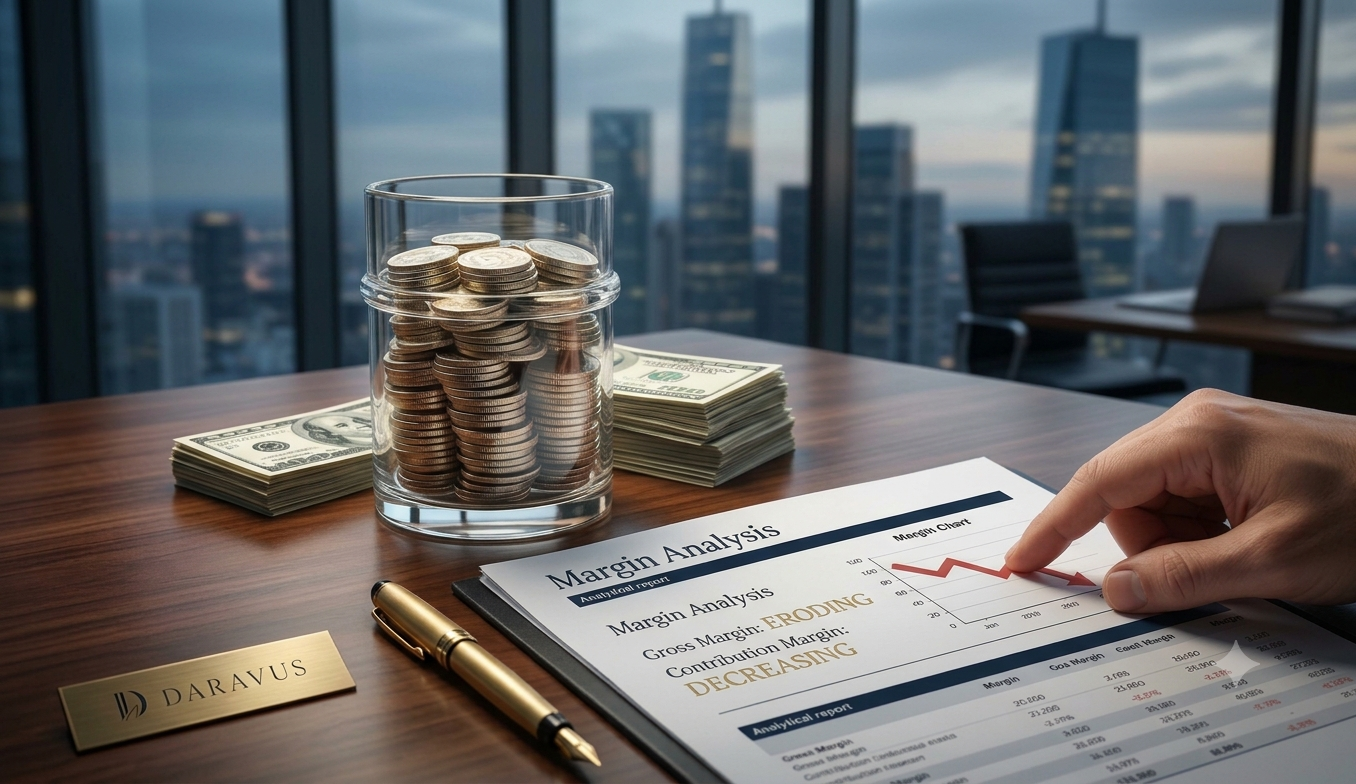
Why positive cash flow can hide weak margins
Healthy cash can mask margins that quietly erode enterprise value — and where to look first.
By Felipe Tocci · Mar 18, 2026 · 6 min read
Few numbers reassure a business owner like a growing cash balance. Money comes in, bills are paid, a reserve is left at month-end — and it feels like the business is doing well. In most capital decisions, that is precisely the reading that misleads the most.
Cash is a symptom, not a diagnosis
Cash measures liquidity: how much money came in and went out over a period. Margin measures efficiency: how much of every dollar of revenue converts into value after costs and expenses. They are different dimensions, and one can hide the other for months or years.
A company can generate positive cash while destroying margin — growing revenue, stretching supplier terms, deferring investment or consuming working capital. Cash goes up; the quality of earnings goes down.
Does your company generate cash because the business model is healthy, or because cash has not yet reflected a structural problem?
Why cash is slow to tell the truth
Cash flow is sensitive to temporary decisions unrelated to the health of the operation. Factoring receivables, stretching payables, reducing inventory or postponing capex improves cash in the short term without improving — and sometimes while worsening — structural margin.
When the capital decision arrives — a sale, a raise, an acquisition — the buyer or investor does not look at the monthly balance. They look at normalized margin, quality of earnings and the conversion of EBITDA into cash over time. That is where the gap between cash and margin surfaces, and charges its price on valuation.
Five warning signs
- Revenue grows, but gross margin falls quarter after quarter.
- Cash improves right after stretching supplier terms.
- Discounts and commercial terms widen to sustain volume.
- Working capital consumes every additional dollar of revenue.
- EBITDA rises, but little of it converts into free cash.
Two cash balances, two values
Two companies with the same positive cash can be worth very different amounts. The gap is not in the balance — it is in the margin.
Company A
Strong cash, fragile margin
- Positive cash sustained by terms and working capital
- Gross margin declining, diluted by discounts
- Low conversion of EBITDA into free cash
- Fragile valuation under diligence
Company B
Solid margin, real value
- Positive cash generated by the operation
- Stable, defensible margin by line
- High conversion of EBITDA into free cash
- A narrative that holds up to a buyer or investor
Where to look first
Six readings, in order, to separate cash from quality of earnings.
1
Gross Margin
Revenue less direct costs. The first place erosion shows up.
2
Contribution Margin
How much each product or client contributes after variable costs.
3
EBITDA
Operating result before interest, taxes, depreciation and amortization.
4
EBITDA → Cash Conversion
How much of EBITDA actually becomes cash in the period.
5
Working Capital
How much the operation consumes to sustain growth.
6
Free Cash Flow
The cash left after maintaining and growing the business.
What to do with this reading
The goal is not to distrust cash, but to understand what sustains it. When margin and cash conversion tell the same story, positive cash is a sign of a healthy model. When they tell different stories, a structural problem is being financed by time — and time, in capital decisions, is expensive.
Before selling, raising, buying or expanding, it is worth rebuilding true margin by line and measuring how much of the result actually becomes cash. It is the difference between deciding with a number that reassures and deciding with a number that supports the choice.
References
Turn financial information into strategic decisions.
At Daravus we help CEOs, boards and growing companies identify the financial signals that precede value loss — and the opportunities to create wealth.